
These findings suggest that the transfer of control rights after violations of debt covenants allows banks to play an active role in disciplining managers’ behaviour and reducing firms’ earnings management through enhanced monitoring. Our study makes an important contribution to a growing literature on the governance and control role of creditors. Although theoretical literature suggests that financial intermediaries have advantages in performing monitoring roles on borrowers (e.g., Diamond 1984), empirical evidence on this appears to be limited. Creditors are thought to be passive in monitoring firms until firms are in default (Nini et al. 2012).
Upgrading to a paid membership gives you access to our extensive collection of plug-and-play Templates designed to power your performance—as well as CFI’s full course catalog and accredited Certification Programs. Take your learning and productivity to the next management accounting level with our Premium Templates. Access and download collection of free Templates to help power your productivity and performance. Managerial accounting also includes reviewing the trendline for certain expenses as well as investigating unusual deviations.
Planning and Policy Formulation
In addition to the financial gauges, organizations are now measuring efficiencies, customer development, employee retention, and sustainability. One planning tool is the budgeting process, which requires management to assess the resources—for example, time, money, and number and type of employees needed—to meet current-year objectives. Finally, managerial accounting information often takes the form of nonfinancial measures. For example, Sportswear Company might measure the percentage of defective products produced or the percentage of on-time deliveries to customers. This kind of nonfinancial information comes from the managerial accounting function. Managerial accounting focuses on internal users—executives, product managers, sales managers, and any other personnel within the organization who use accounting information to make important decisions.
From an agency theory perspective, corporate governance research focuses on monitoring as one of the main solutions to the agency problem (Rutherford et al. 2007), while creditors are thought to be passive until firms are in default (Nini et al. 2012). However, creditors can play an active monitoring role even before a payment default. Timeliness is how quickly information is available to users of accounting information. The less timely (thus resulting in older information), the less useful information is for decision-making.
Tasks and services provided
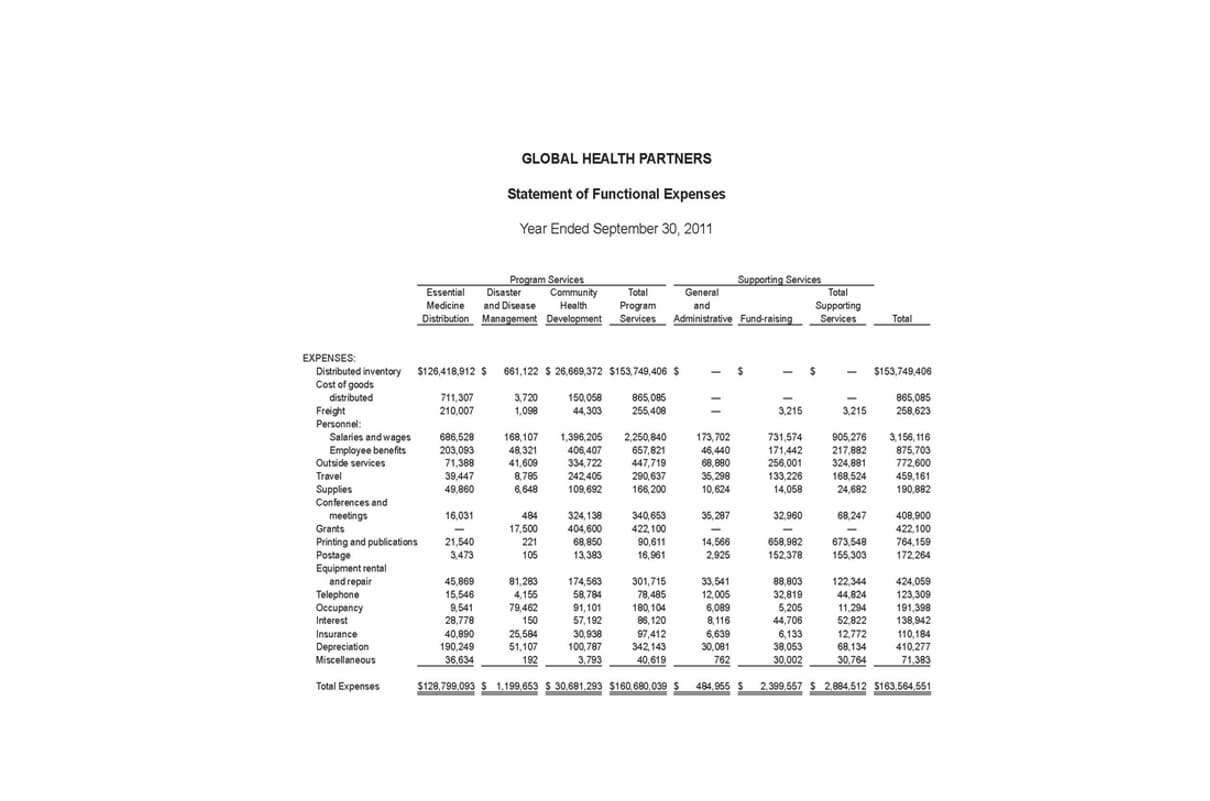
It is important to review this information regularly because expenses that vary considerably from what is typically expected are commonly questioned during external financial audits. This field of accounting also utilizes previous period information to calculate and project future financial information. This may include the use of historical pricing, sales volumes, geographical locations, customer tendencies, or financial information. Performance measures such as return on equity, debt to equity, and return on invested capital help management identify key information about borrowed capital, prior to relaying these statistics to outside sources. It is important for management to review ratios and statistics regularly to be able to appropriately answer questions from its board of directors, investors, and creditors. Installation of Management Accounting involves huge expenditure because of the elaborate organisation needed and the large number of changes in procedures, forms and rules.
Take free trial right away, and make the most of the software for the future of your business. This process of preparing reports about business operations also help forecast cash flows and their impact in the long run. Managers can plan their strategies as they’d have an understanding and predict the revenue source and also know where the company will incur additional expenses from. Using analytical techniques, a managerial accountant can also assess performance discrepancies and run a comparative analysis between two periods to identify and conclude why, what went wrong. The management accountant improves an organization’s efficiency and profits by providing various coordination tools such as budgeting, financial reporting, financial analysis and interpretation, and so on. It aids management by reconciling cost and financial records, preparing budgets and establishing standard costs, and analysing cost deviations to enable management by exception.
Inventory Turnover Analysis
These bills can be classified as bad debts or provisions can be created for such losses in the books of accounts depending on the results of ageing analysis. If there are too many defaulters who fail to pay the money, they owe you, then the company may need a much more stringent process with tighter credit policies to ensure optimum cash flow. If late payments become habitual to businesses/individuals, it may have a negative impact in your business eventually. Reviewing the constraints within a production line or sales process is also a part of Managerial accounting. It involves determining where bottlenecks occur and calculating the impact of these constraints on revenue, profit, and cash flow. This information is useful to implement changes and improve efficiencies in the production or sales process.
- Management accounting, on the other hand, is the presentation of financial data and business activities for the internal management of the organization.
- Personal ‘Prejudices’ and ‘Bias’ of individuals can affect the objectivity and effectiveness of the conclusions and recommendations.
- In this way, the efficiency of employees is improved in the organization as a whole.
- It presents accounting information in a form that enables the management, investors, and creditors to analyze the financial statements.
- In management accounting, the financial information and non financial information is presented at regular intervals say weekly, fortnightly to the management.